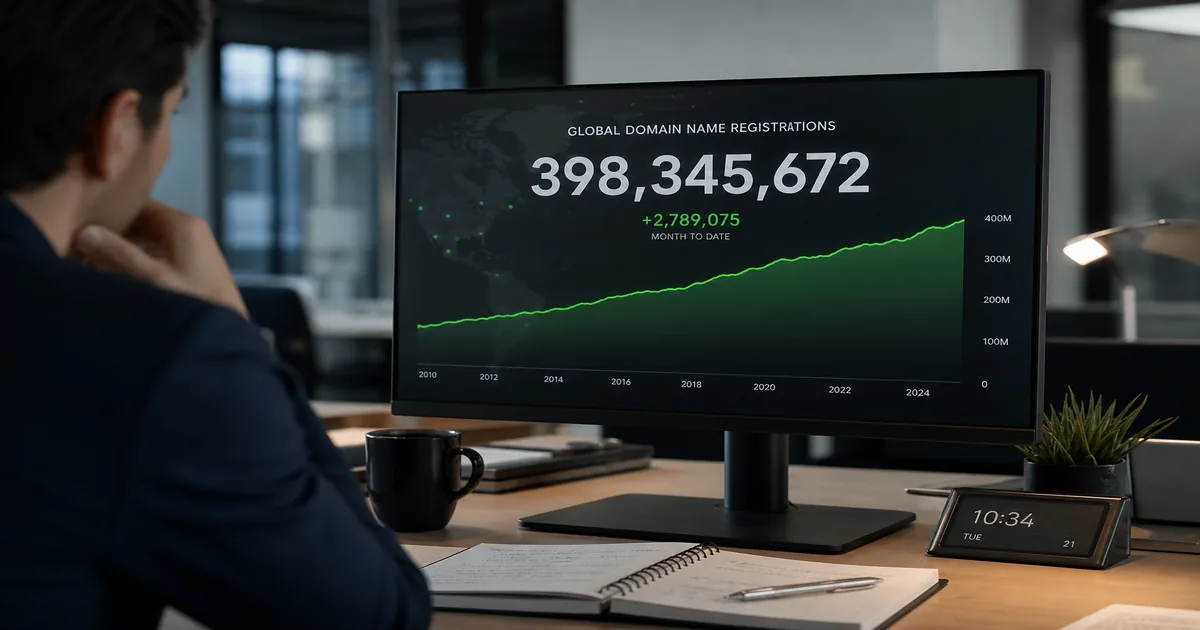
The global domain name base just crossed 400 million registrations. I saw the number in Verisign's latest industry brief and had the same reaction I always have at these milestones: a shrug, then a spreadsheet.
Four hundred million sounds enormous. It is enormous. But domain investing was never about counting every string on the internet. It was about owning the few names that still matter when a founder, a fund, or a Fortune 500 brand decides they cannot launch on a hyphenated compromise.
That distinction matters more in 2026 than it did five years ago. Growth is still happening - mostly in ccTLDs, new gTLDs, and defensive corporate registrations - while the supply of short, clean, category-defining .com and premium alt-TLD names keeps shrinking in relative terms. My take: the 400M headline is noise. The scarcity signal underneath it is the trade.
What pushed the domain base past 400 million?
Verisign's Domain Name Industry Brief tracks aggregate registrations across major TLDs. The .com and .net base alone sits north of 170 million. Add country-code extensions, the long tail of new gTLDs, and the steady drip of brand-defensive registrations, and you get a number that climbs every quarter even when individual investors complain that "everything good is taken."
Both things are true. Everything good is mostly taken - by end users, by funds, or by patient holders who priced correctly years ago. And the total count still rises because businesses register variants, typos, campaign microsites, and portfolio blocks they'll never develop.
I ran my own rough math last week. If you strip parked inventory, obvious bulk keyword junk, and expired-and-reregistered churn, the pool of names you'd actually want in a curated marketplace is tiny. Maybe low six figures globally for English-brandable inventory worth five figures or more. That is not 400 million. That is a boutique market wearing a stadium jacket.
Total registrations measure activity. Premium scarcity measures value. Investors confuse them at their own expense.
Does more supply kill premium domain prices?
Not in the segments where I actually deploy capital.
When a startup needs a credible brand on day one, they are not shopping among 400 million options. They are shopping among twelve names their team can pronounce in a pitch, spell in an email, and defend in a trademark search. That funnel collapses fast.
NameBio and DNJournal comps still show strong clearing prices for short .com, quality .ai, and clean .app names in SaaS and AI categories. The DNJournal charts are not printing median sales at $500 for one-word tech brands. They're printing outliers north of six figures and a thick band of four- and five-figure retail deals that never hit the weekly headlines.
More registrations can pressure the bottom - the $12 hand-reg flip market, the long-tail exact-match SEO plays, the disposable campaign domains. I don't live there. If you browse our current premium inventory, you're looking at the opposite end: names selected because they compress a category story into one memorable string.
Full disclosure: I passed on a decent two-word .com in March because I thought "the market is too big now." It sold privately in June for more than my ceiling. The 400M stat didn't hurt that seller. My hesitation did.
What this means for domain investors in 2026
Here's how I'm adjusting posture after the milestone - not panicking, not pretending growth stopped mattering.
Quality over quantity, aggressively
Renewal math gets ugly on a 2,000-name junk portfolio. At 400M total registrations, the penalty for holding mediocre inventory is higher because buyers have more ways to find "good enough" cheap names. Your listing needs to be obviously better - shorter, cleaner, more category-native.
Watch extension divergence
.com still anchors trust for global brands. .ai carries category heat. .app signals product software. The aggregate 400M number hides that winners and losers inside the TLD stack are diverging, not converging. I am overweight quality alt-TLDs with clear buyer personas - like FounderAi.app for AI founders who want instant positioning without fighting a dictionary-word .com auction.
Treat aftermarket liquidity as the real metric
Registrations are supply. Closed sales are demand. Track both. When supply headlines scream "saturation," demand data often whispers "not for the good stuff." Our market insights section exists because narrative and transaction reality drift apart every quarter.
Where are the real bottlenecks now?
Short .com inventory at the left of the keyboard is effectively a closed club. Two-letter and three-letter .com sales still clear at prices that make normal humans dizzy. Four-letter pronounceable names trade like small real estate lots in good zip codes.
New gTLD growth adds surface area, not substitutes. A founder can register something clever on a fresh extension for $30 and still lose the board meeting to a competitor on a clean .com or .ai. That dynamic preserves premium tiers even as the denominator balloons.
Another bottleneck: operator attention. Founders are busier. They will pay to skip six weeks of naming workshops. That is why curated marketplaces - with brand cards, startup angles, and escrow-ready checkout - keep gaining share against raw WHOIS hunting.
If you're monitoring acquisition mechanics, our acquisition FAQ walks through how we verify listings and route buyers through trusted escrow. Boring process matters more as the market gets noisier.
The ccTLD layer nobody talks about at dinner parties
A meaningful chunk of the march toward 400M comes from country-code growth - not from your neighbor hand-registering another hyphenated .com. Germany's .de, the UK's .uk, Brazil's .br, India's .in: local businesses registering locally because Google and payment processors in those markets reward geographic trust signals.
That does not dilute your premium .com holdings in New York or London. It does explain why global headline numbers feel disconnected from the English-brandable aftermarket you actually trade. I separate "world registrations" from "my market" in every quarterly review. You should too.
When analysts cite 400M, ask which TLDs drove the quarter. Verisign's brief breaks out .com/.net separately for a reason - those lines still tell the story American and European investors care about most.
Are premium AI and SaaS domains still scarce at 400M?
Absolutely - in the segments where we list inventory. Two-syllable .ai names with product fit are harder to source than they were in 2023. Founders arrive with funding and leave empty-handed after two weeks of WHOIS frustration. That frustration is your pricing power as a seller.
SaaS naming patterns compressed around short verbs and ops language - grip, flow, hub, stack. The good ones on .app and .com did not multiply because total registrations rose. If anything, rising registration volume makes mediocre names harder to sell because buyers can always register a longer alternative for $12 and pretend they are happy.
Your job is to own the name they will upgrade to in six months when the $12 option embarrasses them in a sales demo. That upgrade path is still wide open in 2026.
Should you change your buying strategy?
If you're buying $10 hand-regs hoping for lottery tickets, maybe tighten criteria. The long tail is crowded. If you're buying defensible brandables with clear end-user paths - AI tools, fintech workflows, security training - the 400M figure changes almost nothing about your thesis.
I am buying fewer names and paying more for conviction. One excellent SaaS-brandable beats ten "maybe" keyword pairs. I am also watching expired drops more selectively. Churn rises with the base; not every dropped name is a bargain. Some are dropped for a reason.
My forward call: public registration counts will hit 450M without materially depressing top-tier aftermarket prices. The gap between "a domain exists" and "the right domain is available" will keep widening. That is the investable edge.
If you've been sitting on cash waiting for the market to "flood," you might be waiting forever while the names you actually want keep appreciating. Browse, compare, make a shortlist. The denominator is huge. Your shortlist shouldn't be.
- DN Detector editorial